

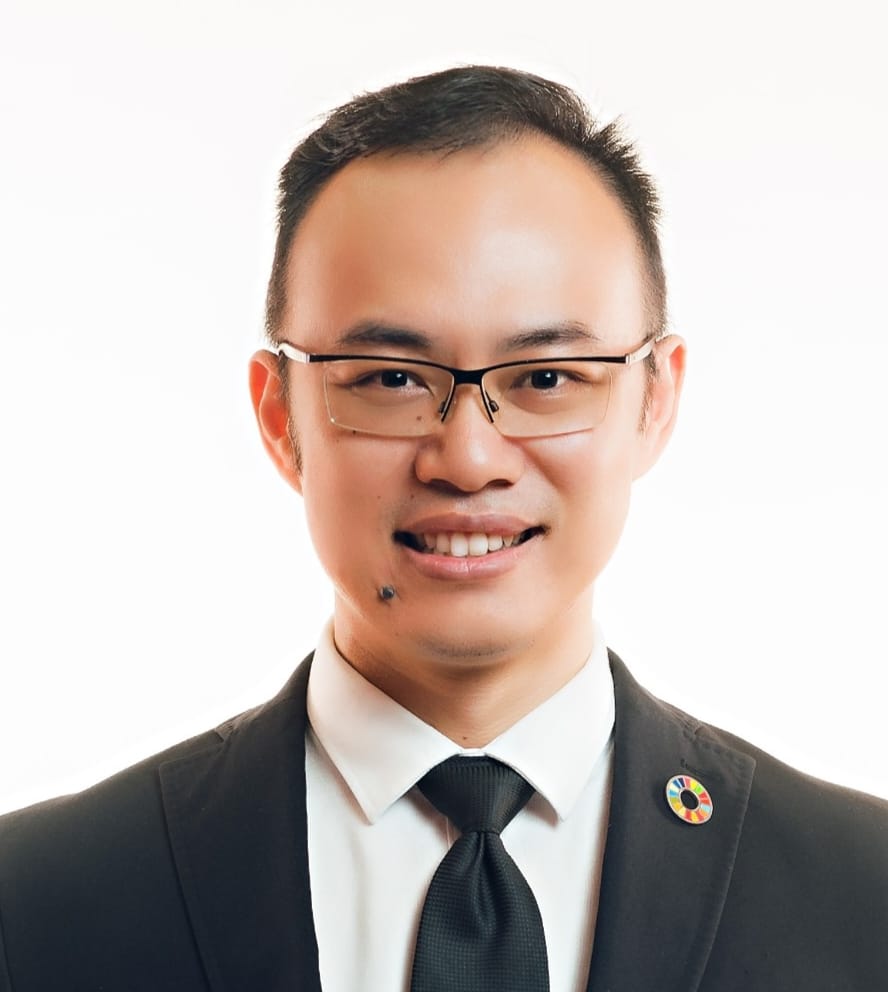
Jefery Tan
LABUAN: Ahead of Budget 2027 on 9 October, the SME Association of Labuan has
called for two measures to keep Labuan competitive.
The first is applying the Service Tax exemption under Section 48 of the Service Tax Act 2018 to services performed in Labuan.
The second is waiving
import duty on goods made by Labuan MSMEs and sold to the rest of Malaysia.
The Association also welcomed the announcement by YB Steven Sim, Minister of Entrepreneur
Development and Cooperatives, that the Cabinet has agreed to exempt MSMEs from the new
minimum wage increase.
“This decision shows the Government’s clear understanding of the pressures small businesses face,”
said Jefery Tan, President of the SME Association of Labuan.
The same understanding can make a real difference in Labuan, where businesses carry the additional costs of operating on an island.”
Applying Section 48 in Labuan as Designated Area
Section 48 provides that no service tax is charged on services provided within a Designated Area.
Work carried out entirely within Labuan by Labuan businesses should therefore not attract service tax, even
where the customer is registered elsewhere in Malaysia.
Most if not all of major industry players here are registered on the mainland.
YB Hannah Yeoh, the Federal Territories Minister, set up the Labuan Industry Task Force in February
2026.
Since then, the Association has engaged with Perbadanan Labuan, the Royal Malaysian Customs Department and the Ministry of Finance.
The Association believes Budget 2027 is the right moment
to settle the matter.
Major industry players often award large, multi-disciplinary contracts to contractors based elsewhere
in Malaysia, which then engage Labuan service providers to carry out a portion of the work.
If Section 48 is applied as intended, the major industry players pay service tax only once, on the contractor’s
invoice.
If not, they pay tax on a price that already includes tax. At 8%, every RM100,000 of work by
Labuan service providers adds RM8,640 to their cost, of which RM640 is tax charged on tax.
“Section 48 has been in the law since 2018,” Mr Tan said.
Applying it as intended ensures major industries are not paying tax on tax for work done on their own premises, which are located at
Designated Area, and that engaging local service providers remains the natural choice.”
